
Identify the species before the policy

Insurance for rabbits, birds and other exotic pets

An exotic-pet label is too broad to establish eligibility. Match the animal, state and actual contract before comparing benefits.

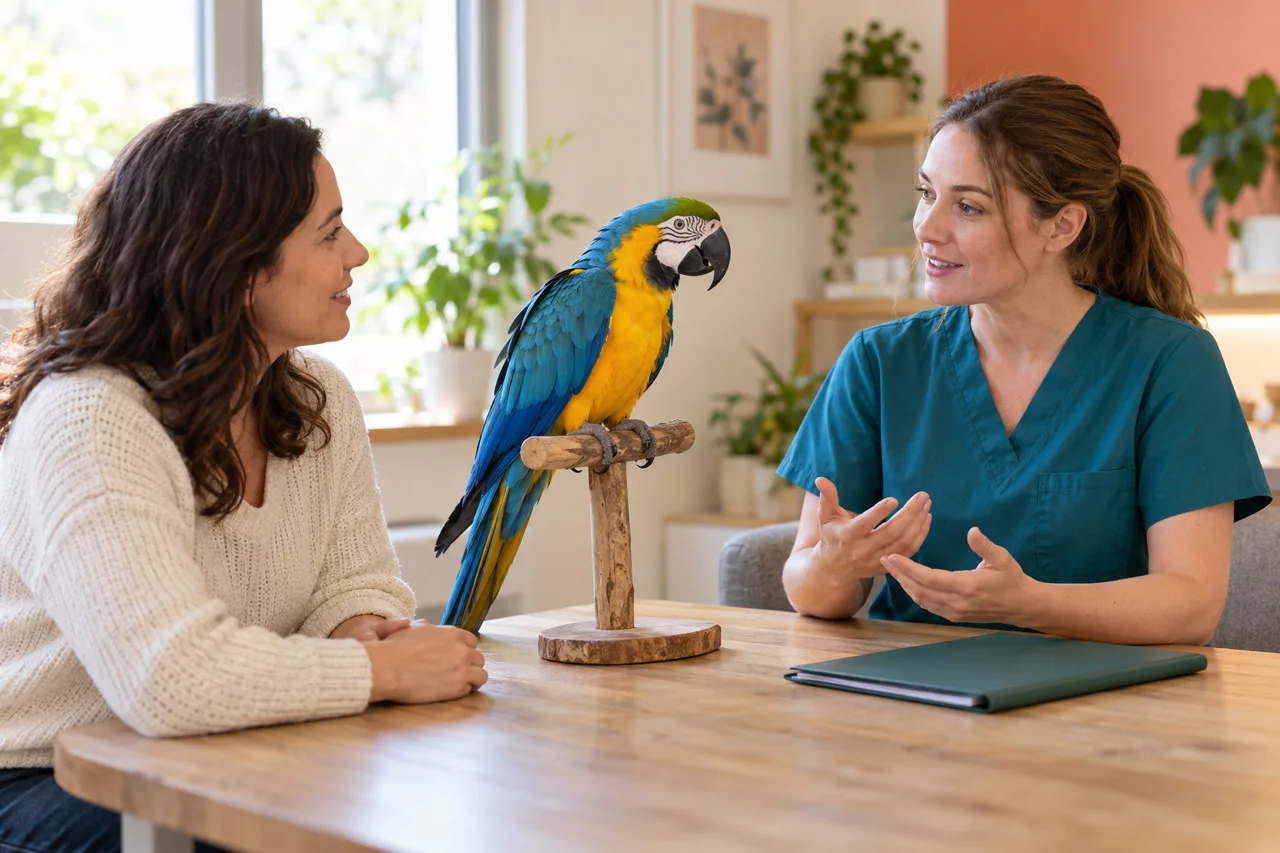
Blue-and-gold macaw on a perch between its owner and a veterinarian
✓ Policy-first ✓ Independent ✓ Useful checks
Direct answer
Insurance is available for some exotic pets, but eligibility is species- and provider-specific. Nationwide advertises avian and exotic coverage, and MetLife lists certain rabbits, reptiles, ferrets and birds with state limitations.
What to know

Use the exact animal identity

Begin with the species, age, ownership status and your state. A seller’s reference to reptiles does not mean every reptile is accepted; a bird category does not establish acceptance of every bird. Ask about the actual animal rather than choosing the nearest dog or cat entry in a quote form.

Also clarify whether the animal is a household companion or used for breeding, exhibition or another purpose. Where an application asks about use or history, answer accurately. Do not assume a pet nickname conveys the species information needed for underwriting.

Get an explicit eligibility answer before spending time comparing reimbursement percentages. A generous-looking dog policy offers no useful protection for a rabbit it cannot insure.

Coverage

Two official starting points, with limited conclusions

Provider What its current material establishes What still needs confirmation
Nationwide Offers avian and exotic pet coverage Exact species, state, available contract and underwriting outcome
MetLife Describes certain rabbits, reptiles, ferrets and birds Exotic availability in your state and the specific animal’s eligibility

This is not a comprehensive market ranking. It also avoids repeating a provider’s “only insurer” marketing as a market fact: more than one official provider page now describes exotic options. The relevant next step is a species-specific offer, not a superlative.

Ask for the specimen contract and any species or state endorsement. Do not import deductible, preventive-care or family-plan features from the provider’s dog-and-cat pages unless the exotic offer itself includes them.

What to know

Clinic capability and insurance eligibility are different tests

Find a veterinarian who actually treats your species and ask where it refers emergencies or advanced cases. For birds, CDC specifically recommends a veterinarian experienced with pet birds. The fact that a policy permits a licensed veterinarian does not tell you whether every local clinic has the equipment or experience for that animal.

For a planned specialist visit, ask how the insurer treats referral consultations, diagnostics, hospitalization and prescribed medicines. Keep travel and other nonmedical costs separate until the contract explicitly addresses them.

The bird photograph is an illustration of a consultation, not proof of a diagnosis or insurance approval. For an animal needing care now, contact a suitable veterinary service rather than waiting to find a new policy.

What to know

A compact exotic-policy interview

  • Does the declaration identify this species correctly?
  • What does the policy consider pre-existing, including earlier signs and treatment?
  • Are there condition or service schedules in addition to the overall limit?
  • How are the deductible and reimbursement applied?
  • What preventive services, if any, are listed separately?
  • Are dental, reproductive or husbandry-related exclusions relevant to this animal?
  • What records and pharmacy documentation are needed?
  • Must I pay the clinic first, and when is a claim due?

These questions do not imply that any named insurer includes or excludes each category. They identify the terms to inspect before assuming an exotic policy works like a familiar dog or cat plan.

What to know

If no suitable policy is offered

Ask whether the obstacle is species eligibility, location, age, history or the requested level of protection. That answer determines whether another offer is worth investigating or whether the available policies simply do not address your need.

A discount arrangement or prepaid clinic package is not automatically an insurance substitute. Check what it actually provides, where it can be used and what large treatment costs remain yours.

You can still prepare a care plan: identify the appropriate routine and emergency clinics, keep prior records accessible, and create a reserve based on your veterinarian’s estimates for anticipated care. Do not treat a dog-and-cat affiliate link as the next step for an animal it cannot cover.

Evidence

Sources and policy context

These public references support the consumer or veterinary context. Named insurer details were checked in official product materials; the policy offered for your pet and state determines the actual terms.

Next step

Compare Current Pet Insurance Rates

Check current options for your pet and location, then compare the policy details, exclusions, costs, and eligibility before choosing.

Compare the policy before you choose Check the actual offer, exclusions and out-of-pocket terms.
See Rate Options